Retirement Income Planning

Independent retirement income advice

Approaching retirement?
Make sense of your pensions.

Not sure what income your pensions could give you, or what to do next? We help you understand what you have, compare your choices and put a clear plan in place.

Start with our new business team. No obligation. Any fees for further advice are explained before you commit.
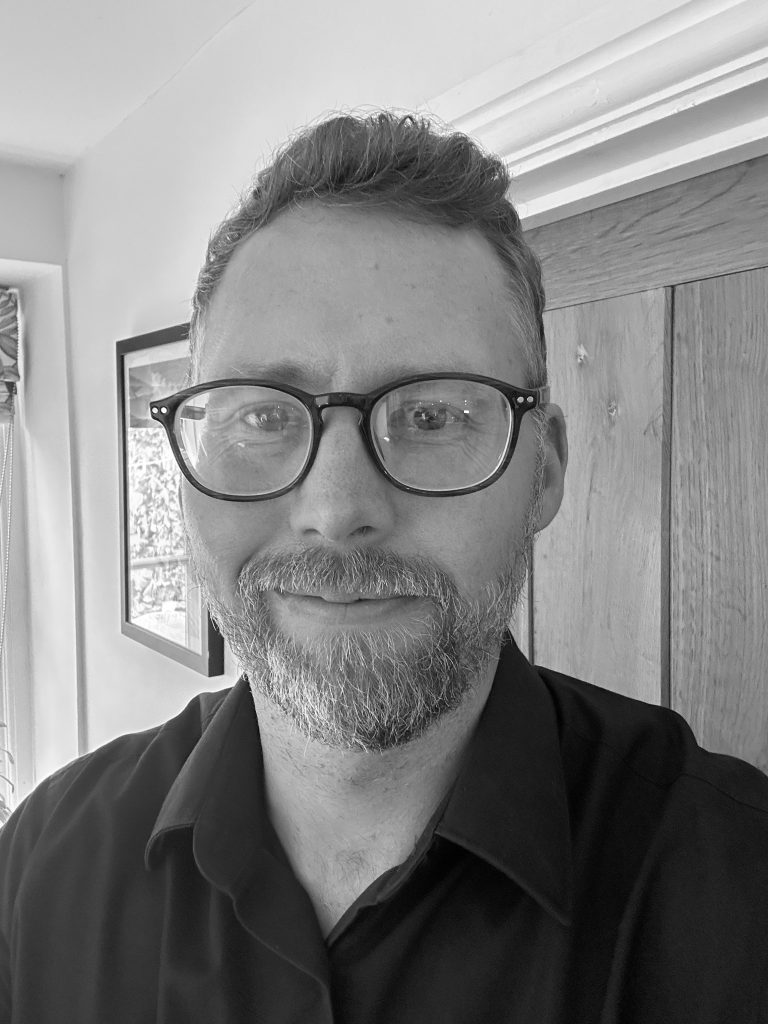
Joe Ricks, Director and Independent Financial Adviser at Mather and Murray Financial
Real people. Personal advice.
Joe Ricks · Director & Independent Financial Adviser
One of the MMF team helping clients plan for retirement.
Independent financial adviceFCA authorised · FRN 696226Based in Cricklade · Clients across the UK

An experience shared by an MMF client

“Kate produced a plan for my pension that fulfilled all I required.”

Jonathan Crowe
Excerpt from a client review displayed on the MMF website.

This is one client’s experience, not a promise of the same outcome or investment performance.

Read more client reviews

What happens on the first call?

Our new business team will listen to your enquiry and explain how we can help. If an adviser appointment is appropriate, we will explain the next steps and any fees for further advice before you commit.

The initial phone conversation is free and without obligation. It is not a personalised pension recommendation.

Prefer to choose a time now? Book your initial call.

Take the first step

Let’s talk about your retirement.

Leave your details and tell us what you would like help with. Our team will explain the next step.

Please do not include policy numbers, bank details, medical information or documents in your enquiry.

We use your details to respond to your enquiry. Read our privacy policy. Prefer to call? 01793 261626 · Mon–Fri, 9am–5pm.

From pension pots to a plan

You do not need to have all the answers.

You may have pensions from several jobs, a retirement date in mind and questions you have been putting off. That is a useful place to start.

  • “Can I afford to retire when I want to?”
  • “What could my pensions pay each month?”
  • “Should I combine my pension pots?”
  • “Annuity, drawdown or a lump sum?”

Choices explained in plain English

More than one way to fund retirement.

You may not need to choose just one. We help you weigh certainty, flexibility, tax and what you want to leave for others.

Annuities

Exchange some or all of a pension for contractual income. A lifetime annuity can pay for life; fixed-term arrangements work differently.

Check inflation, partner benefits and existing guarantees. Access to the money used is normally lost, and the decision is usually irreversible after the cooling-off period.

Explore annuity advice

Drawdown

Keep money invested and take withdrawals to suit your plans, subject to scheme rules.

Flexibility comes with investment risk. Charges, losses and withdrawals can reduce your pension and the money could run out.

Compare annuity, drawdown or a combination

Lump sums

Take money as lump sums, including UFPLS where available and suitable, rather than committing to one income pattern.

Withdrawals can affect tax, future pension contributions and how long your savings last. We help you consider the wider picture.

Several pensions do not automatically mean you should consolidate. We check charges, guarantees, protected benefits and your income needs before recommending whether a move is suitable. Defined benefit pensions require a different assessment. Read the pension consolidation checks or explore final salary pension options.

Not ready to enquire? Explore the retirement options hub.

Before you get in touch

A few common questions.

Do I need to know which pensions I have?

Bring what you have to the conversation. We can explain what information will be useful for an adviser review; you do not need to choose an income option before speaking to us.

Will you recommend combining all my pensions?

Only if it is suitable. Existing pensions can include valuable guarantees, protected benefits or favourable charges. Keeping some or all of them may be appropriate.

Can I use an annuity and drawdown together?

Potentially. Some people use contractual income for essential spending and keep other money flexible. Suitability depends on your pensions, needs, tax position and attitude to risk.

Do I have to be ready to retire now?

No. Planning ahead can help you understand your options and the decisions you may face. Tell us your intended timetable, even if it is still uncertain.

Will I speak to an adviser on the free initial call?

The initial call is with our new business team. They will understand your enquiry and explain how to arrange an adviser appointment, including any fees for further advice.